Introduction
For homeowners, the phrase Guaranteed Rebuilding Cost Coverage offers a significant sense of security. It suggests that in the event of a total loss, the insurer will cover the bill to rebuild the home, regardless of the final price tag. However, a recent decision from the Supreme Court of Canada has clarified that the word guaranteed does not necessarily override specific exclusions found elsewhere in an insurance policy.
In Emond v. Trillium Mutual Insurance Co., 2026 SCC 3, the Court addressed the interplay between a generous endorsement and a restrictive exclusion clause. The decision provides essential guidance for insurance professionals and policyholders across Canada, including British Columbia, regarding how standard form contracts are interpreted when coverage grants and exclusions appear to conflict.
The Facts of the Case
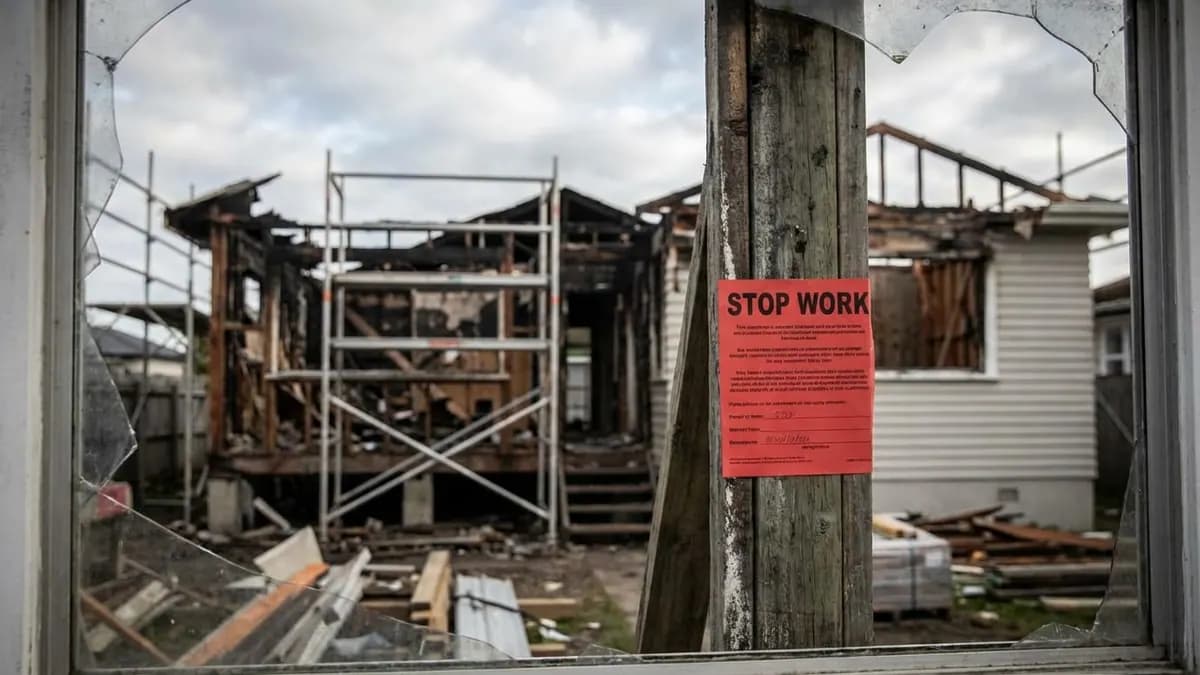
The appellants, Stephen and Claudette Emond, owned a home built in 1968 located on the Ottawa River. In April 2019, catastrophic flooding destroyed the property, resulting in a total loss. The Emonds held a comprehensive homeowners policy with Trillium Mutual Insurance Company. Crucially, they had purchased a Guaranteed Rebuilding Cost endorsement, often referred to as a GRC endorsement.
The dispute arose not over the loss itself, but over the cost of reconstruction. Because the home was located within a regulated area, the local conservation authority required significant and expensive upgrades to rebuild the home in compliance with current development standards. The Emonds sought coverage for these additional compliance costs under their GRC endorsement.
Trillium denied this specific portion of the claim. They relied on a clause in the base policy—the compliance cost exclusion—which stated that the insurer would not pay for increased costs of repair or replacement due to the operation of any law regulating zoning, demolition, or construction. The insurer argued that while the GRC endorsement removed the monetary limit on the policy, it did not erase the standard exclusions found in the main policy wording.
The Supreme Court Decision
In a majority decision penned by Justice Rowe, the Supreme Court of Canada dismissed the Emonds' appeal. The Court held that the compliance cost exclusion applied despite the existence of the Guaranteed Rebuilding Cost endorsement. Consequently, the Emonds were not entitled to recover the increased costs associated with meeting the conservation authority's requirements, other than a small limited amount provided by a separate coverage extension.
The Court applied the interpretive framework established in Ledcor Construction Ltd. v. Northbridge Indemnity Insurance Co., 2016 SCC 37. The analysis focused on reading the contract as a whole to determine if the language was ambiguous.
Interpreting the Endorsement
The majority found that the GRC endorsement was not a standalone contract but an amendment to the base policy. The endorsement explicitly stated that it amended the Basis of Claim Payment provision but also included a critical caveat: in all other respects, the policy provisions and limits of liability remain unchanged.
The Court reasoned that the purpose of the GRC endorsement was to remove the specific dollar limit on the declaration page, protecting the insured from inflation or under-insurance. However, it did not grant carte blanche coverage for excluded perils or excluded costs. The phrase guaranteed referred to the amount of insurance, not the scope of perils or excluded costs. Furthermore, the Court interpreted the phrase current building techniques found in the endorsement to refer to modern construction methods (such as using nail guns rather than hammers), rather than a promise to pay for regulatory compliance upgrades.
The Nullification of Coverage Doctrine
The Emonds argued that applying the exclusion would render their guaranteed coverage nugatory, invoking the nullification of coverage doctrine. This legal principle prevents insurers from relying on exclusions that would effectively nullify the very coverage the policyholder intended to buy.
The Court rejected this argument. Justice Rowe explained that the exclusion did not completely defeat the objective of the GRC endorsement. The homeowners still received a significant benefit: they could recover replacement costs exceeding the face value of the policy for the structure itself, provided those costs were not specifically excluded. Because the endorsement still provided value—protection against inflation and under-valuation of the main structure—the coverage was not nullified.
Implications for Canadian Law
This decision reinforces the primacy of the written text in standard form insurance contracts. For legal practitioners and insureds in British Columbia and across Canada, Emond v. Trillium highlights that an endorsement cannot be read in isolation. The generally advisable order of interpretation requires looking at the coverage grant, then the exclusions, and then any exceptions to the exclusions.
The ruling clarifies that the term guaranteed in an insurance context is often a defined term of art rather than a literal promise of total indemnity. It signifies that the monetary cap is lifted, but the contractual terms regarding what is and is not covered remain in force. Additionally, the decision narrows the scope of the nullification of coverage doctrine, signaling that courts will be hesitant to apply it unless an exclusion truly renders the purchased coverage meaningless.
Practical Advice for Policyholders
This case serves as a stark reminder of the importance of reviewing the fine print regarding bylaw and code compliance. Many older homes in British Columbia may require significant upgrades to meet modern seismic, electrical, or zoning codes if rebuilt today.
Policyholders should verify if their policy includes specific coverage for Bylaw and Code Compliance. In the Emond case, there was a specific extension for this, but it was capped at $10,000, which was insufficient for the required upgrades. Homeowners should ask their brokers specifically about coverage for increased costs due to the operation of laws or bylaws, rather than assuming a Guaranteed Replacement Cost endorsement covers regulatory upgrades. If a property is subject to strict conservation or zoning rules, seeking specialized endorsements that explicitly cover these compliance costs is essential.